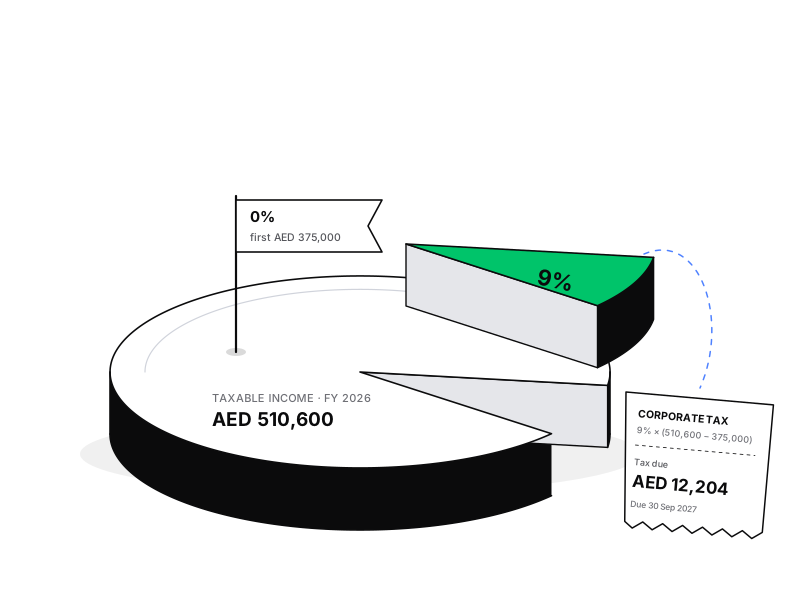
UAE Corporate Tax for small businesses
Corporate Tax,
worked out.
What the 9% actually applies to, who has to register, when the return is due, how Small Business Relief works, and how fylng estimates your number from bank statements.
Last checked 20 Nov 2026 against FTA and Ministry of Finance sources. Not tax advice.
Know where your books stand first.
Upload a bank statement and your receipts. The free check shows what is missing or unclear before you work out taxable income. No sign-up, deleted after 24 hours.
Most small companies register, file once a year and pay little or nothing. The penalties come from skipping the paperwork.
Register
Every company, free zone entity and branch registers with the FTA on EmaraTax. Individuals only once business turnover passes AED 1M in a calendar year.
Work out taxable income
Start from your accounting profit, add back what the law won't let you deduct, take off exempt income and losses.
Apply the rate
0% on the first AED 375,000 of taxable income, 9% on the rest. Or elect Small Business Relief if revenue is AED 3M or less.
File and pay
One return per financial year, due with the payment within 9 months of the year end. Zero tax still means a return.
A flat floor, then 9% on every dirham above it
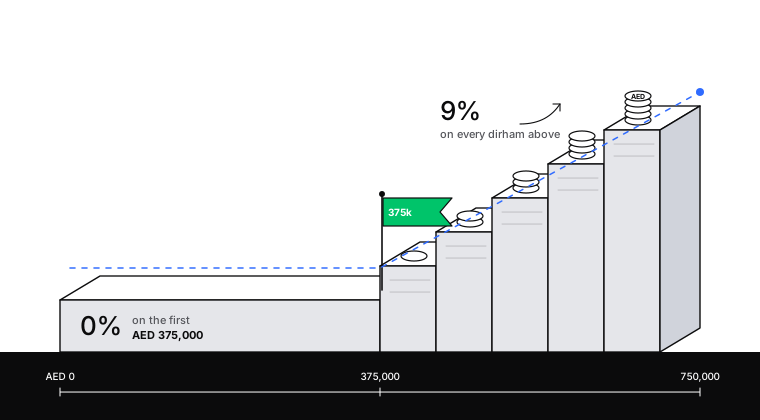
Federal Decree-Law 47 of 2022 sets two rates for ordinary businesses: 0% on taxable income up to AED 375,000 and 9% on the part above. It is not a cliff. Earn AED 376,000 and you pay 9% on AED 1,000, which is AED 90.
The tax applies to taxable income, which is profit after adjustments. Not revenue, not cash in the bank. A Dubai agency billing AED 2M with AED 1.7M of costs is taxed on roughly AED 300,000, and pays nothing.
| Taxable income | Tax at 9% over 375k | Effective |
|---|---|---|
| AED 300,000 | AED 0 | 0% |
| AED 500,000 | AED 11,250 | 2.25% |
| AED 1,000,000 | AED 56,250 | 5.6% |
| AED 3,000,000 | AED 236,250 | 7.9% |
Do I need to register and file?
Walk down the rows. Most owners stop at row one.
Registration deadlines
The FTA fixed these in Decision 3 of 2024. The deadlines for companies that already existed on 1 March 2024 ran out in 2024. For everyone since:
| Who | Deadline |
|---|---|
| Company set up in the UAE on or after 1 Mar 2024 (mainland or free zone) | 3 months from incorporation or licence |
| Resident individual whose business turnover passed AED 1M in a calendar year | 31 March of the following year |
| Non-resident individual | 3 months from meeting the conditions |
Late registration: AED 10,000, sometimes waived
Missing the deadline costs a flat AED 10,000 (Cabinet Decision 75 of 2023, as amended by Cabinet Decision 10 of 2024).
The FTA runs a waiver initiative: if you file your first tax return (or annual declaration, for exempt persons) within 7 months of the end of your first tax period, the penalty is waived, or refunded to your tax account if already paid. No separate request is needed. The FTA page, updated 26 Oct 2026, gives no closing date; check it before you count on it.
Your tax period is your financial year. Count nine months.

The return and the payment share one deadline: 9 months after the tax period ends (Articles 48 and 53). Most UAE companies use a calendar year, so FY 2026 is due on 30 September 2027.
Key dates, December year end, FY 2026
- 1 Jan 2026Tax period starts. Keep every invoice and bank statement from today.
- 31 Dec 2026Year end. Revenue for the year decides whether you can elect Small Business Relief.
- 31 Mar 2027Individuals whose 2026 business turnover passed AED 1M register by today.
- 31 Jul 20277 months: if 2026 was your first tax period and you registered late, file by today for the penalty waiver.
- 30 Sep 2027Return filed and tax paid on EmaraTax. Month nine.
- 1 Oct 2027Late filing penalty starts at AED 500 a month; unpaid tax attracts 14% a year, charged monthly.
- 31 Dec 2033Seven years after year end: earliest date you can bin FY 2026 records.
Revenue under AED 3M? You can be treated as having no taxable income.
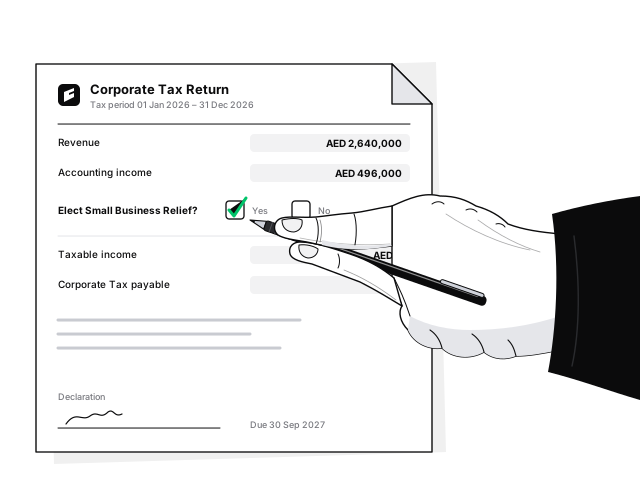
Small Business Relief (Article 21 of the law, Ministerial Decision 73 of 2023) lets a resident taxable person elect to be treated as having no taxable income for a tax period. Tax due: zero, no matter how profitable the year was.
Extended to 2029. On 7 August 2026 the Ministry of Finance announced Ministerial Decision 131 of 2026: the relief now covers tax periods ending on or before 31 December 2029 (it was 31 December 2026). The AED 3,000,000 revenue threshold did not change.
You qualify if
- Revenue is AED 3,000,000 or less in this tax period and every previous one. Cross it once and the relief is gone for good.
- You are not a Qualifying Free Zone Person and not part of a multinational group with consolidated revenue over AED 3.15 billion.
- You elect it in the return. It is not automatic, and you still register and file.
What you give up for that year
- Losses from an SBR year can't be carried forward. Elect it in a loss year and that loss is wasted.
- Disallowed net interest from that year can't be carried forward either.
- Exempt income rules, reliefs and deductions don't apply; you simply report no taxable income.
On the plus side, the transfer pricing disclosure form (Article 55) does not apply in an SBR year, and the return is simpler. Splitting one business into several companies to stay under AED 3M is treated as an abuse arrangement.
A free zone licence is not a 0% guarantee
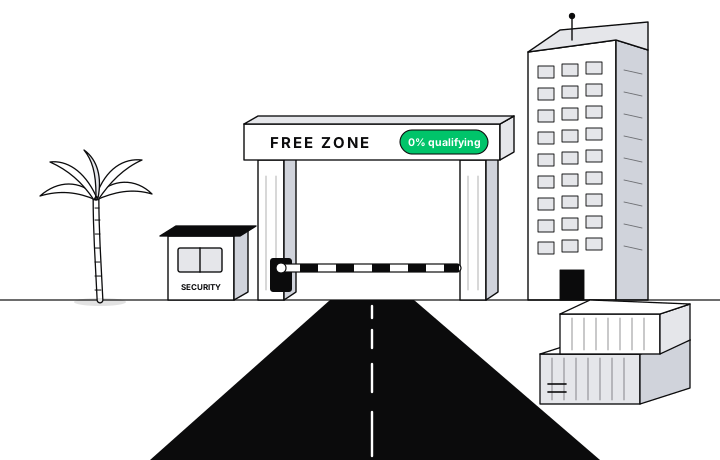
A Qualifying Free Zone Person (QFZP) pays 0% on qualifying income and 9% on the rest, with no AED 375,000 band. To be one, the company has to keep adequate substance in the zone, earn qualifying income, not elect into the normal regime, meet the arm's length rules and keep audited financial statements.
Qualifying income broadly means income from other free zone persons, and from qualifying activities (manufacturing, trading of qualifying commodities, logistics, treasury, distribution from a designated zone and others listed in Ministerial Decision 229 of 2025). Selling goods or services to mainland customers is often not qualifying.
A QFZP cannot elect Small Business Relief. A free zone company that is not a QFZP is taxed like a mainland one and can, if it meets the revenue test.
Ordinary business costs go in. A short list stays out.
Expenses are deductible when incurred wholly and exclusively for the business and not capital in nature. Rent, salaries, DEWA or SEWA, e& and du bills, Salik tolls, ENOC fuel, Careem rides for work, Google Ads: all fine. Articles 32 and 33 list what isn't.
| Item | Deductible |
|---|---|
| Client, supplier or shareholder entertainment (meals, hotel, tickets) | 50% |
| Staff meals and team events | 100% |
| Fines and penalties (traffic, municipality, FTA) | 0% |
| Bribes or other illicit payments | 0% |
| Dividends and profit distributions to owners | 0% |
| Donations to an entity that isn't a Qualifying Public Benefit Entity | 0% |
| Recoverable input VAT | 0% |
| Corporate tax itself, and foreign income tax | 0% |
| Laptop, car, fit-out | Via depreciation |
Compensation for damages or breach of contract is not a "fine" and can be deductible. Staff entertainment is our reading of Article 32, which targets customers, shareholders, suppliers and business partners.
Interest
Net interest above AED 12M a year is capped at 30% of tax-adjusted EBITDA; the excess carries forward for 10 years. Below AED 12M, no cap. Almost no small business hits it.
Connected persons and market value
Payments to a connected person (an owner, director, officer, or someone related to them) are deductible only up to market value and only if they are for the business. A salary of AED 60,000 a month to the owner's cousin for part-time admin will be cut back. Deals with related parties must also be at arm's length.
Transfer pricing paperwork (brief)
- Disclosure form with the return: related-party transactions over AED 40M in total, or payments to connected persons over AED 500,000.
- Master file and local file: only if revenue is AED 200M or more, or the group's is AED 3.15bn or more (Ministerial Decision 97 of 2023).
A small Sharjah trading company, from profit to tax
Example figures, not a real client. "Gulf Line Trading LLC" buys and sells packaging in Sharjah. Mainland licence, calendar year, VAT-registered, revenue under AED 3M in every year since it opened.
| 1 | Revenue | 2,640,000 |
| Cost of goods sold | (1,716,000) | |
| 2 | Gross profit | 924,000 |
| Warehouse and office rent | (96,000) | |
| Salaries (4 staff) | (228,000) | |
| SEWA, e& and du | (20,400) | |
| Client entertainment | (18,000) | |
| Traffic and municipality fines | (3,600) | |
| Depreciation (van, laptops) | (22,000) | |
| Other admin (incl. AED 2,000 donation) | (40,000) | |
| 3 | Accounting profit | 496,000 |
| Add back 50% of client entertainment | +9,000 | |
| Add back fines | +3,600 | |
| Add back donation to non-qualifying body | +2,000 | |
| 4 | Taxable income | 510,600 |
| Less 0% band | (375,000) | |
| 5 | Taxed at 9% | 135,600 |
| 6 | Corporate tax due 30 Sep 2027 | 12,204 |
Scenario A Normal rules
9% of AED 135,600. That is 2.5% of accounting profit, thanks to the 0% band.
Scenario B SBR elected
Revenue AED 2,640,000 is under AED 3M this year and every year before, so the company elects Small Business Relief. Same return deadline. Saving: AED 12,204.
Scenario C Over 3M
Had revenue been AED 3,050,000, SBR would be off the table for 2026 and every later year, even if sales fall back. Back to Scenario A maths.
Under AED 3M revenue, you may keep books on a cash basis
Ministerial Decision 114 of 2023 lets a business with revenue of AED 3,000,000 or less prepare its financial statements on a cash basis: income when the money arrives, costs when you pay. Above that, accrual accounting (IFRS, or IFRS for SMEs up to AED 50M revenue) is required unless the FTA approves otherwise.
Cash basis is simpler but can move profit between years. An invoice to a Dubai client in December 2026, paid in January 2027, lands in 2027.
Same AED 3M figure as Small Business Relief, but a separate rule. You can use cash basis without electing SBR, or elect SBR while keeping accrual books.
Your estimate, all year, from the bank lines you already have
1. Every line gets a CT treatment
Statements, receipts and invoices are sorted into a 39-account UAE chart. Each account carries its corporate tax treatment: fully deductible, 50% (client entertainment), or not deductible (fines).
2. Add-backs are worked out for you
Revenue and costs are taken net of recoverable VAT. The non-deductible share of each expense is added back to reach taxable income.
3. 0% band, 9% and the SBR check
fylng applies the AED 375,000 band, shows tax with and without relief, and checks the year's revenue against AED 3M. You confirm earlier years. Free zone companies are flagged for a QFZP review instead of being given 0%.
4. Honest about what it can't see
It's a cash-basis estimate. Unpaid invoices at year end, prepayments and depreciation are not adjusted yet, and fixed asset purchases are flagged so you don't deduct them in full. A full CT return pack is Coming soon
Keep it for seven years. File even when it's zero.
Losses
A tax loss carries forward with no time limit, but can only wipe out 75% of a later year's taxable income (Article 37). Lose AED 200,000 in 2026 and make AED 200,000 in 2027: you can use AED 150,000 of the loss, and AED 50,000 of 2027 income is still taxable (at 0%, under the band). Ownership must stay at least 50% the same, or the business must carry on the same activity. Losses from SBR years don't carry forward.
Records
Keep everything that supports the return for 7 years after the end of the tax period (Article 56): bank statements, tax invoices, contracts, payroll, asset registers. Provide them in Arabic if the FTA asks.
Corporate tax penalties now
| Registering late | AED 10,000 |
| Return filed late | AED 500 / month for 12 months, then AED 1,000 / month |
| Tax paid late | 14% a year, charged monthly |
| Incorrect return not fixed before the deadline | AED 500 |
| Error fixed by voluntary disclosure | 1% of the difference per month |
| Error found in an FTA audit first | 15% of the difference + 1% / month |
| Records not kept | AED 10,000 (AED 20,000 if repeated within 24 months) |
| Records not given in Arabic on request | AED 5,000 |
Cabinet Decision 75 of 2023 as amended by Cabinet Decision 10 of 2024. The April 2026 penalty reform (Cabinet Decision 129 of 2025) changed the VAT, excise and tax procedures schedule, not this one.
 12Common mistakes
Ten things we see small companies get wrong
"SBR means I don't file"
Relief is elected inside the return. No return, no relief, and a late filing penalty on top.
Using the VAT TRN
Corporate tax has its own registration and number on EmaraTax. Being VAT-registered doesn't cover it.
Testing profit against 3M
The SBR and cash-basis tests use revenue. A trader with AED 3.2M sales and AED 150k profit doesn't qualify.
Claiming all client entertainment
Lunch with a client at a Dubai Mall restaurant is 50% deductible. Staff meals are not limited in the same way.
Deducting fines
Speeding, parking, Salik violations, municipality and FTA penalties are all added back. Normal Salik tolls are fine.
Expensing a new van in one go
A AED 90,000 delivery van is deducted through depreciation over its life, not in the year you pay for it.
Personal spending in the company account
The family's Carrefour shop or a home DEWA bill isn't for the business. Take it as drawings or dividends, which aren't deductible.
Paying relatives above market rate
Payments to connected persons are deductible only up to market value. Keep contracts and a reason for the amount.
Assuming free zone = 0%
Mainland sales can break the de minimis test and push the whole company onto 9% for five years.
Electing SBR in a loss year
The loss can't be carried forward. If you expect profits above AED 375,000 later, compare before you tick the box.
Corporate tax
questions
I'm a freelancer earning AED 600,000 a year. Do I register?+
No. Individuals only come into corporate tax when business turnover in a calendar year exceeds AED 1,000,000 (Cabinet Decision 49 of 2023). Salary, personal investment income and income from property you hold privately are left out of that count. If you trade through an LLC instead, the company registers whatever its size.
We made a loss. Do we still file?+
Yes. Every registered taxable person files a return for each tax period. Filing the loss year is also how you keep the loss for later years (unless you elect Small Business Relief for that year).
When is my first return due?+
Nine months after the end of your first tax period. For a company formed in March 2025 with a December year end, the first period may run to 31 December 2025 (or be extended), so the return would be due 30 September 2026. Check the period shown on your EmaraTax registration.
Can a free zone company elect Small Business Relief?+
Not if it is a Qualifying Free Zone Person. A free zone company that isn't a QFZP is taxed like a mainland company and can elect SBR if its revenue has never been above AED 3M.
Is the salary I pay myself deductible?+
A market-rate salary to a working owner of a company can be deductible, because you are a connected person and the market value test applies. Dividends and profit distributions are never deductible. Sole establishments taxed as natural persons can't deduct drawings.
Does fylng file my corporate tax return?+
No. fylng gives you a running estimate, the add-backs and an SBR eligibility check, with every number traced to its source lines. You file on EmaraTax yourself or through your tax agent. A full CT return pack is coming soon.
Is Small Business Relief really extended?+
Yes. The Ministry of Finance announced Ministerial Decision 131 of 2026 on 7 August 2026: the relief applies to tax periods ending on or before 31 December 2029, with the same AED 3M revenue limit.
Sources
Last checked 20 Nov 2026. Rules change; confirm on tax.gov.ae or with your tax agent before you file. If something here differs from the FTA, the FTA is right.
- Federal Decree-Law No. 47 of 2022 on the Taxation of Corporations and Businesses (Ministry of Finance, English translation): Articles 3, 21, 30, 32, 33, 37, 48, 53, 55, 56.
- MoF: Small Business Relief extended until 31 December 2029 (Ministerial Decision 131 of 2026, 7 Aug 2026).
- MoF: Ministerial Decision 73 of 2023 on Small Business Relief (AED 3M, exclusions, artificial separation).
- FTA: Waiver of late registration penalties (page updated 26 Oct 2026).
- Cabinet Decision 75 of 2023 and its amendments (corporate tax penalties schedule).
- MoF: Ministerial Decision 114 of 2023 on accounting standards and methods (cash basis up to AED 3M).
- MoF: Cabinet Decision 49 of 2023 on natural persons (AED 1M turnover).
- Ministerial Decision 229 of 2025 on qualifying and excluded activities (free zones, de minimis).
- MoF: Ministerial Decision 97 of 2023 on transfer pricing documentation.
- KPMG: FTA Decision 3 of 2024, registration timelines.
- Deloitte: transfer pricing disclosures in the tax return (AED 40M / AED 500,000 thresholds).
- PwC Worldwide Tax Summaries: UAE deductions and tax administration (interest AED 12M, losses, 9-month filing, records).